What is the scope and industry significance of the Ferro Manganese Market?
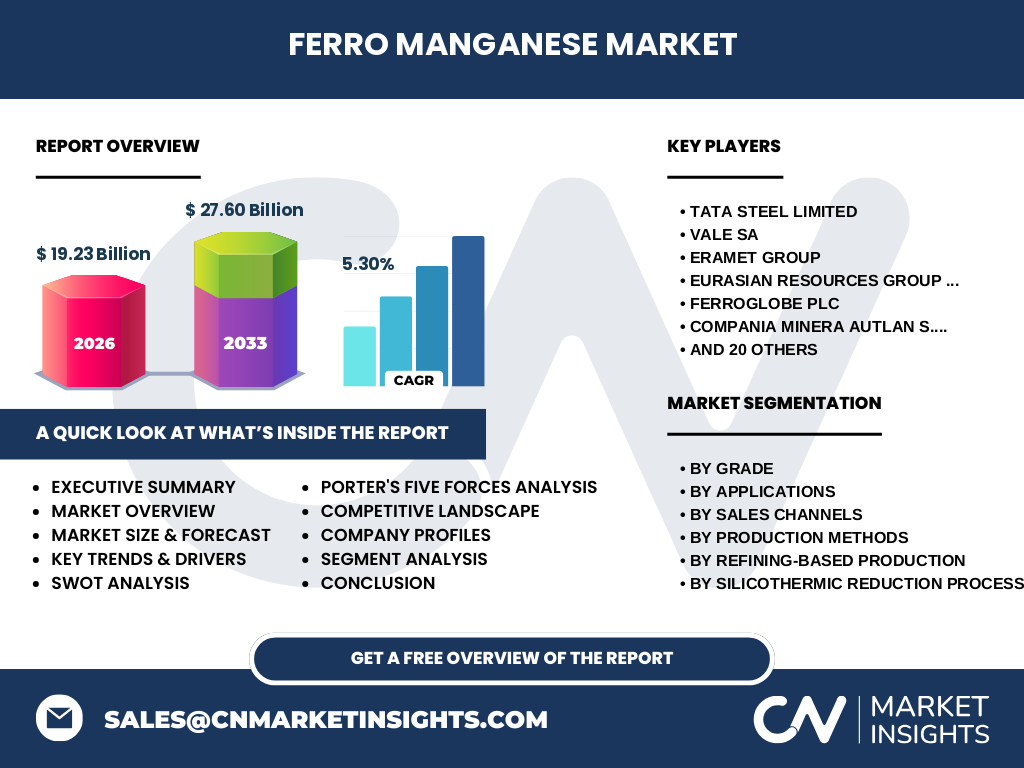
Our analysis indicates that the Ferro Manganese Market encompasses critical metallurgical inputs essential for global steelmaking, valued at $19.23 Billion in 2026. This sector drives structural integrity across construction and automotive supply chains by acting as a primary deoxidizer, desulfurizer, and alloying element additive.
Structural Growth Drivers and Market Restraints
The market is propelled by surging global infrastructure investments and rising automotive production. However, energy-intensive production methods like Submerged Arc Furnace (SAF) and Blast Furnace operations face stringent environmental regulations from bodies like the EPA and EU, creating localized production bottlenecks.
Emerging Trends in the Ferro Manganese Industry
Industry trends highlight a strategic shift toward low-carbon and ultra-low carbon specialty grades produced via advanced silicothermic reduction and refining processes. Producers are increasingly adopting green energy to power Electric Arc Furnace (EAF) facilities, mitigating carbon tax impacts.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted manganese ore supply chains from key ports in South Africa and Australia, halting blast furnace operations globally. Post-pandemic recovery has been robust, driven by fiscal stimulus packages targeting heavy infrastructure and accelerated steel demand.
Competitive Landscape and Strategic Dynamics
The competitive landscape features consolidated giants like Tata Steel Limited, Eramet Group, and Glencore plc controlling substantial supply volumes. These tier-one players leverage vertical integration from captive manganese ore mines to advanced refining facilities to protect profit margins.
Executive Summary of the Ferro Manganese Market
This comprehensive Ferro Manganese Market analysis highlights a thriving sector poised to expand from $19.23 Billion in 2026 to $27.60 Billion by 2033 at a 5.30% CAGR. Strategic positioning in low-carbon production remains paramount for long-term viability.
Market Forecast from 2027 to 2033
Driven by compounding industrial demand across developing economies, the market is projected to reach $27.60 Billion by 2033. This trajectory represents a steady 5.30% CAGR from the 2026 baseline of $19.23 Billion, fueled by advanced steel alloy requirements.
Segmentation Analysis by Grade, Application, and Production
Our segmentation review covers grades from High Carbon to Low Carbon FeMn, applications spanning deoxidizers, desulfurizers, and welding, and diverse production routes. The Carbothermic Reduction (Blast Furnace) and Submerged Arc Furnace (SAF) processes dominate bulk high-carbon output, while EAF and refining methods cater to specialty steel.
Regional Market Analysis and Geographic Distribution
Geographic performance is heavily skewed toward Asia-Pacific, driven by massive steel manufacturing hubs in China and India. North America and Europe maintain steady demand, albeit constrained by strict environmental compliance mandates governing local alloy production.
In-Depth Regional Review of Key Markets
Asia-Pacific dominates consumption through extensive utilization by domestic steel mills. Meanwhile, Latin American producers such as Compania Minera Autlan leverage rich regional ore reserves, exporting refined grades to North American industrial consumers navigating tight trade policies.
Company Profiles and Competitive Benchmarking
Leading industry participants such as Ferroglobe plc, Eurasian Resources Group, and Anglo American plc focus on technological optimization and geographic diversification. Their competitive advantage stems from proprietary refining techniques yielding premium controlled-carbon alloys.
Porter's Five Forces Analysis of the Sector
Bargaining power of raw material suppliers is moderate due to concentrated high-grade manganese ore reserves. Threat of substitutes remains low given the irreplaceable metallurgical role of manganese in steel production, though intensity of rivalry among established smelters is high.
SWOT Analysis of the Ferro Manganese Market
Strengths lie in established supply networks and essential steelmaking utility. Weaknesses involve high energy consumption and carbon intensity. Opportunities emerge from green steel initiatives, while threats include volatile raw material tariffs and stringent global carbon border adjustments.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with mining raw manganese ore, followed by pyrometallurgical smelting via SAF or blast furnaces. Processed alloys flow through direct sales or distributors to end-users in automotive, construction, and specialized welding sectors.
Investment Insights and High-Potential Areas
High-potential investment areas center around proprietary silicothermic reduction technologies and renewable-powered EAF operations. Capital allocation toward low-carbon and specialty grade facilities offers superior insulation against impending regulatory penalties.
Conclusion and Key Takeaways
The Ferro Manganese Market industry trends underscore a pivotal transition toward sustainable metallurgy. Achieving the projected $27.60 Billion valuation by 2033 requires proactive investments in energy-efficient refining and strategic vertical integration.
Research Methodology
Baseline estimates are meticulously triangulated by combining customs trade registry data, primary stakeholder interviews with industry executives, and secondary macroeconomic indicators from global steel associations to ensure high econometric accuracy.
Scope of the Report and Coverage Parameters
This report covers global production, consumption, trade flows, and pricing dynamics across specified grades, applications, and sales channels from 2026 to 2033. Regional evaluations encompass all major producing and consuming nations with verified industrial output.
Recent Developments in the Industry
Recent strategic moves include major capacity expansions by Maithan Alloys Limited and green-tech partnerships forged by Eramet Group to decarbonize alloy refining. These initiatives reflect an industry-wide push toward operational efficiency and strict environmental compliance.